Chance Favors the Prepared: Turning Global Energy Shocks into Scalable Opportunities
Executive Summary
The Dangote Petroleum Refinery and Petrochemicals (DPRP) Initial Public Offering opened on 14th of September 2026 and will close on 13th of October 2026. The company is seeking to raise USD 1.64Bn through 4.1Bn ordinary shares (c. 3.4% float) at an offer price of NGN 525.0 (USD 0.40). The minimum subscription is 10 ordinary shares and 50,000 ordinary shares for retail and institutional investors, respectively. The net offer proceeds will be dedicated to funding part of the USD 14.3 Bn expansion project to double capacity from 700,000 bpd to 1.4 Mn bpd.
Key Investment Thesis:
DPRP operates a single-train refinery with a nameplate capacity of 700,000 bpd, and intends to expand its refining capacity to 1.4Mn bpd. The facility is an unintegrated refinery (it does not own upstream crude oil production and does not own a downstream retail distribution network) with a yield slate concentrated in petrol, diesel, and jet fuel, alongside secondary revenue streams from butane, naphtha, LPG, polypropylene, and propane. By geography, as of 1H26, 56% of sales were in Nigeria and 44% in export markets. Cost of sales (made up mainly of crude feedstock acquisitions) remains the core margin determinant. Capital intensity will continue to weigh on free cash flow generation over the medium term. Looking ahead, guidance points to heavy capital deployment, though actual execution spend could realistically exceed management projections. Primary investment risks encompass: (i) operational vulnerabilities inherent in a single-train refinery configuration and crude oil availability, (ii) regulatory & antitrust friction, (iii) material contingent liabilities from ongoing claims and litigation, and (iv) liquidity risks stemming from the tightly restricted public float.
Macro Context
The transaction comes amid significant disruptions to global energy markets, driven by regional conflicts in the Middle East and ongoing strikes on Eastern European energy infrastructure. These geopolitical bottlenecks have restricted flows through maritime chokepoints like the Strait of Hormuz and curtailed refining output across Eurasia. Situated outside Persian Gulf risk zones, DPRP’s mega-refinery at Lekki, Nigeria, has emerged as a major commercial beneficiary of these trade realignments. As an Atlantic Basin hub, the facility surpassed U.S. exporters in mid-2026 to become Europe’s single largest supplier of jet fuel. Concurrently, West African and broader Sub-Saharan economies have increasingly pivoted to DPRP for long-term offtake of motor spirit, diesel, and aviation fuel, establishing regional energy security corridors.
Valuation
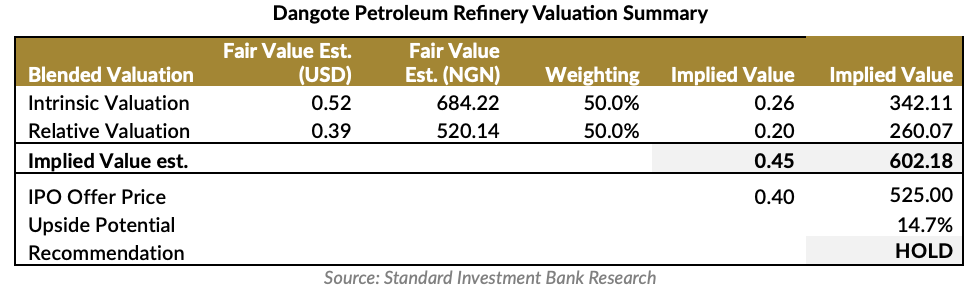
We performed a blended valuation for the business, taking into account relative and intrinsic methodologies to estimate the fair value on all likely fronts. Our model supports a HOLD recommendation, identifying an implied upside of +14.7% against the NGN 525.00 offer price. While relative peer multiples indicate near-term FY26 earnings are fully valued, intrinsic cash flow modelling suggests that the long-term cash flow expansion associated with doubling refinery capacity to 1.4 Mn bpd is not yet fully priced into the offer.