Summary Tables – NSE Performance
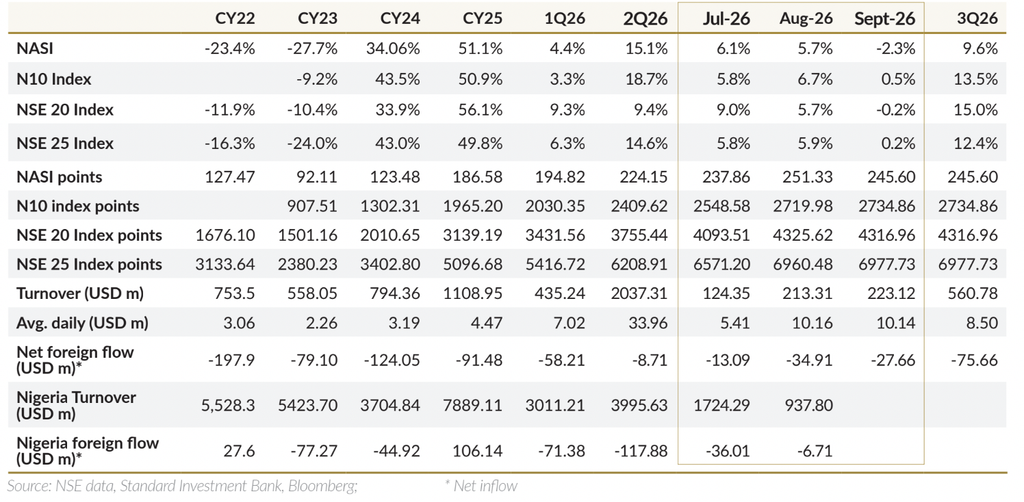
The bourse closed September on a bearish note, with the broad market contracting 2.3% m/m – a sharp reversal from the +5.7% m/m and +6.1% m/m gains recorded in August and July, respectively. Other key indices delivered mixed results: while the NSE 20 fell by 0.2% m/m, the N10 and NSE 25 posted modest gains of 0.5% m/m and 0.2% m/m, respectively.
For 3Q26, benchmark indices delivered robust quarterly capital gains. The NSE 20 accelerated its momentum—advancing 15.0% q/q to outpace its performance in both 1Q26 and 2Q26. Conversely, while the NASI (+9.6% q/q), N10 (+13.5% q/q), and NSE 25 (+12.4% q/q) posted strong quarterly growth, their expansion trailed the peak levels reached in 2Q26.
Profit-taking emerged as a dominant theme throughout the quarter, as investors continued to lock in returns following the bull run in prior quarters. In line with expectations, foreign activity remained net-negative, recording net capital outflows of USD 75.7Mn in 3Q26.
Safaricom was the top traded stock in the quarter, accounting for 22.3% of the overall turnover, with banking stocks topping the majority of the top traded list – activity being concentrated on KCB Group, Equity Group, and ABSA. Africa Mega Agricorp was the quarter’s top gainer, soaring 218.4% q/q to KES 354.25. Home Afrika, on the other hand, shed 20.7% q/q to KES 1.07, closing as the top loser.
Looking ahead, we anticipate 4Q26 to close on a bullish note – with profit-taking activities being salient as investors rebalance their books. That said, geopolitics remains a prevailing risk, which may thaw bullish sentiments, in the case of an advancement. From a corporate action vantage point, November takes the centre stage in the quarter, with banking sector 3Q25 and Safaricom 1H27 earnings expected in the month.
During the past month;
- Britam Holdings completed capital restructuring
Britam Holdings PLC officially executed a reduction of its share premium account by KES 5,875,252,000—lowering it from KES 13,237,451,000 to KES 7,362,199,000—which took effect on 7 September 2026 following shareholder approval, High Court confirmation, and registration by the Registrar of Companies. The transaction directly offset and eliminated the company’s accumulated losses, leaving total equity, net assets, and overall shareholding structure unchanged. In our view, clearing these historical losses is a strategic precursor to normalizing the balance sheet and paving the way for a resumption of dividend distributions. - Change of guard at Centum & notice of reclassification adjustments to FY26 audited statements
Centum Investment Company PLC announced that Dr. James Mworia stepped down after nearly 18 years as Group Chief Executive Officer & Managing Director to serve as the founding CEO of the National Infrastructure Fund (NIF). To maintain operational continuity, the Board appointed Mr. Thomas Omondi-Achola—Centum’s Group COO —as Acting Group CEO with immediate effect.
Also, during the month, Centum notified shareholders and the investing public that it made reclassification adjustments to the presentation of Other Comprehensive Income (OCI) in its separate financial statements for the year ended 31 March 2026 (originally published on 30 July 2026) following its auditor’s review of the Integrated Report. The adjustments, which account for a group reorganization involving subsidiary Vipingo Development Ltd and the presentation of reserves from the disposal of Bakki Holdco Limited, pertain strictly to the separate financial statements and have zero impact on the previously published consolidated (group) financial statements or other components of the company’s financial results. - High Court nullified Government’s 15% divestiture in Safaricom
According to a public announcement by Safaricom, the High Court of Kenya ruled against the Government of Kenya’s 15% divestiture of its shareholding in Safaricom to Vodafone Kenya Limited and, effectively, Vodacom Group Limited on 15th September 2026. The transaction had been completed on 30th June 2026 following the lifting of conservatory orders by the Court of Appeal and the fulfilment of relevant conditions precedent. Safaricom has noted that it is reviewing the judgment and its implications. Given that the matter remains subject to legal processes, further updates will be provided in due course and as appropriate. Worth noting, Vodacom Group said it will appeal the decision. - Quickmart announced its intention to list on the NSE
Quickmart announced its intention, in conjunction with a proposed offer for sale of existing ordinary shares by its sole shareholder, Sokoni Retail Kenya Limited, to list all of its issued ordinary share capital on the Main Investment Market Segment of the Nairobi Securities Exchange PLC.
In line with this announcement, Quick Mart has launched its Initial Public Offering (IPO) to sell 2,000,000,000 existing ordinary shares (a 50% stake) at KES 7.50 per share, seeking to raise KES 15 billion and valuing the retailer at KES 30 billion. The offer is non-underwritten and open from 5 October 2026 to 30 October 2026, subject to a 75% minimum subscription threshold. The International Finance Corporation (IFC) serves as a cornerstone investor with a conditional commitment of up to USD 15.0 million, while selling shareholder Sokoni Retail Kenya Limited is bound by a 24-month lock-up on 60% of its remaining post-offer shares. Trading on the NSE is expected to commence on 12 November 2026 following allotment, and CDS account crediting on 11 November 2026.
We published;
- Initiation of Coverage Report on The Dangote Petroleum Refinery and Petrochemicals (Nigeria)
The Dangote Petroleum Refinery and Petrochemicals (DPRP) Initial Public Offering opened on 14th of September 2026 and will close on 13th of October 2026. The company is seeking to raise USD 1.64Bn through 4.1Bn ordinary shares (c. 3.4% float) at an offer price of NGN 525.0 (USD 0.40). The minimum subscription is 10 ordinary shares and 50,000 ordinary shares for retail and institutional investors, respectively. The net offer proceeds will be dedicated to funding part of the USD 14.3 Bn expansion project to double capacity from 700,000 bpd to 1.4 Mn bpd.
The transaction comes amid significant disruptions to global energy markets, driven by regional conflicts in the Middle East and ongoing strikes on Eastern European energy infrastructure. These geopolitical bottlenecks have restricted flows through maritime chokepoints like the Strait of Hormuz and curtailed refining output across Eurasia. Situated outside Persian Gulf risk zones, DPRP’s mega-refinery at Lekki, Nigeria, has emerged as a major commercial beneficiary of these trade realignments. As an Atlantic Basin hub, the facility surpassed U.S. exporters in mid-2026 to become Europe’s single largest supplier of jet fuel. Concurrently, West African and broader Sub-Saharan economies have increasingly pivoted to DPRP for long-term offtake of motor spirit, diesel, and aviation fuel, establishing regional energy security corridors.
We performed a blended valuation for the business, taking into account relative and intrinsic methodologies to estimate the fair value on all likely fronts. Our model identifies an implied upside of c. +14.7% against the NGN 525.00 offer price. While relative peer multiples indicate near-term FY26 earnings are fully valued, intrinsic cash flow modelling suggests that the long-term cash flow expansion associated with doubling refinery capacity to 1.4 Mn bpd is not yet fully priced into the offer.
Find the detailed report here.
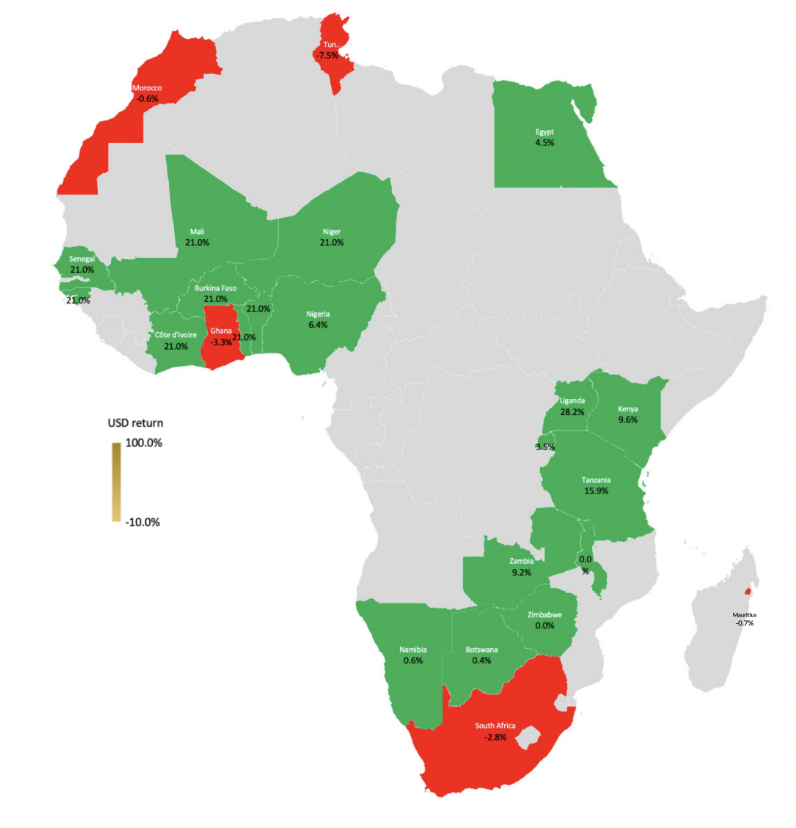
Select African countries’ benchmark index dollar returns 3Q26