Summary Trading Statistics
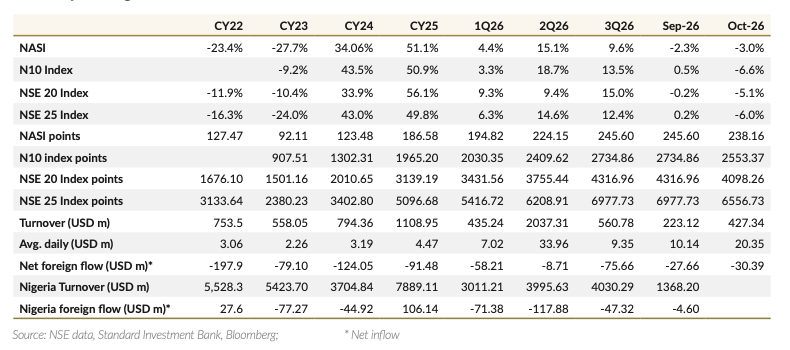
The equities market closed October on a bearish trajectory, with the broad index contracting 3.0% m/m. The market weakness extended across key indices: the N10, NSE 20, and NSE 25 dropped 6.6% m/m, 5.1% m/m, and 6.0% m/m, respectively, signalling a sharper contraction compared to the prior month.
Continued profit-taking across counters – driven by investors seeking to lock in gains from a multi-quarter rally – weighed on market performance. Foreign participation mirrored this cautious sentiment, yielding a net outflow of USD 30.4 Mn.
Turnover was heavily concentrated in Kenya Pipeline Company, which accounted for 77.5% of total turnover following a significant block transaction tied to Dangote’s acquisition of a c. 25% equity stake. Consequently, the counter jumped 66.7% m/m to settle at KES 15.00, sustained by strong buying interest in later sessions.
Olympia Capital Holdings headlined the top performers, appreciating by 145.6% m/m to KES 19.35. Conversely, Shri Krishana Overseas anchored the laggards, losing 19.2% m/m to close at KES 13.85.
During the past month;
- Kakuzi Plc has issued an updated profit warning and cautionary statement advising shareholders and the general public that its net earnings for 2026 are expected to be significantly lower than the previous year. Following an initial notice in August 2026—which projected at least a 25% drop in earnings—the revised guidance comes as a result of a continued downturn in the global macadamia market and reduced macadamia crop yields.
- Sanlam Allianz Holdings (Kenya) PLC issued a cautionary announcement informing shareholders and the public of a proposed internal reorganization to simplify its group corporate structure and boost operational efficiency. Under this plan, the company will acquire the entire long-term life insurance business, including all assets and liabilities, from its wholly owned subsidiary, Sanlam Allianz Life Insurance (Kenya) Limited. Following the transfer and receipt of necessary regulatory approvals, the parent company will operate the insurance business directly, remain listed on the Nairobi Securities Exchange (NSE), and change its name to Sanlam Allianz Life Insurance (Kenya) PLC, while the subsidiary will surrender its license and eventually be dissolved. Existing insurance policies, shareholdings, and company control will remain unaffected. Find the notice here.
- The Nairobi Securities Exchange has announced Dangote Petroleum Refinery’s Initial Public Offer by way of subscription of Kenya Global Depository Receipts. The refinery offered 728,971,962 IPO Shares for 728,971,962 GDR Offering of 728,971,962 Global Depository Receipts at a GDR Subscription Price of KES 53.50 per Global Depository Receipt, targeting KES 39.0bn, subject to a minimum success threshold of KES 50.0m.
- Kenya Airways PLC has issued a material announcement regarding two major government-approved financial measures designed to support its operational turnaround and balance sheet restructuring. The Government of Kenya has approved a 10-year shareholder loan of US$350 million (approx. KES 45.15 billion) to cover immediate operational needs – such as aircraft maintenance and returning grounded planes to service – with an option to convert the debt into equity. Additionally, the government granted in-principle approval to convert existing loans of approximately KES 122 billion (plus accrued interest) into equity-qualifying tradeable instruments.
This balance sheet restructuring aims to move the airline out of negative equity, improve creditworthiness, and facilitate future capital raising and strategic partnerships. Implementation remains subject to definitive agreements as well as shareholder, CMA, and NSE approvals, leading the airline to issue a cautionary notice advising investors to exercise caution when trading its shares.
We published,
- Dangote Petroleum Initiation of Coverage Report. Worth noting;
The company sought to raise USD 1.64Bn through 4.1Bn ordinary shares (c. 3.4% float) at an offer price of NGN 525.0 (USD 0.40). The minimum subscription was 10 ordinary shares and 50,000 ordinary shares for retail and institutional investors, respectively. The net offer proceeds will be dedicated to funding part of the USD 14.3 Bn expansion project to double capacity from 700,000 bpd to 1.4 Mn bpd.
The transaction came amid significant disruptions to global energy markets, driven by regional conflicts in the Middle East and ongoing strikes on Eastern European energy infrastructure. These geopolitical bottlenecks have restricted flows through maritime chokepoints like the Strait of Hormuz and curtailed refining output across Eurasia. Situated outside Persian Gulf risk zones, DPRP’s mega-refinery at Lekki, Nigeria, has emerged as a major commercial beneficiary of these trade realignments. As an Atlantic Basin hub, the facility surpassed U.S. exporters in mid-2026 to become Europe’s single largest supplier of jet fuel. Concurrently, West African and broader Sub-Saharan economies have increasingly pivoted to DPRP for long-term offtake of motor spirit, diesel, and aviation fuel, establishing regional energy security corridors.
Based on the Dangote Petroleum Refinery & Petrochemicals 3Q2026 preliminary headline numbers, we have reviewed our model based on the earnings outperformance and, consequently, our valuation and recommendation. While our core investment thesis remains intact, incorporating these efficiency gains meaningfully enhances DPRP’s free cash flow trajectory. Reflecting these updates, we raise our fair value estimate from USD 0.45 (NGN 602,18) to USD 0.63 (NGN 836.80), unlocking an implied 59.4% upside (up from 14.7%) relative to the offer price. Consequently, we revise our recommendation from a HOLD to a BUY.
Find the detailed IPO report here. Find the valuation update report here. - Quick Mart PLC IPO Report. Worth noting;
The QuickMart PLC Initial Public Offering (IPO) opened on October 5, 2026, and closed on October 30, 2026, with selling shareholder Sokoni Retail Kenya Limited offering 2,000,000,000 ordinary shares (a c. 50% post-offer float) at KES 7.50 per share to raise KES 15.0Bn. Structured strictly as a secondary offer for sale, QuickMart will receive no net proceeds from the transaction; physical store expansion and digital initiatives will remain fully funded through organic operating cash flows and existing credit lines.
The business is Kenya’s second-largest supermarket chain by store count and revenue, operating 73 leased outlets across 16 counties. Its core merchandise strategy focuses on fast-moving consumer goods, with Food (52%) and Fresh Produce (12%–13%) generating c. 65% of total sales. The business operates an asset- light model by leasing 100% of its stores. Managed through a standardized six-month rollout, new stores are reported to achieve EBITDA break-even in their first month, mature within 12 months, and achieve full capital payback within two to three years. Its medium-term strategy centres on expanding its footprint to 125 domestic locations by 2030. Simultaneously, the company plans to scale its digital and e-commerce channel, QSOKO, to contribute over 10% of total revenue.
We performed a blended valuation taking into account intrinsic (DCF & DDM) and relative (P/E, P/B, EV/ EBITDA) methodologies to estimate the fair value of QuickMart PLC. Our model derives a consolidated fair value estimate of KES 7.32 per share. This indicates that the IPO offer price of KES 7.50 per share represents a slight premium (+2.3%) over the blended intrinsic and peer-based valuation, suggesting near-term operational growth and market positioning are fully priced into the offer.
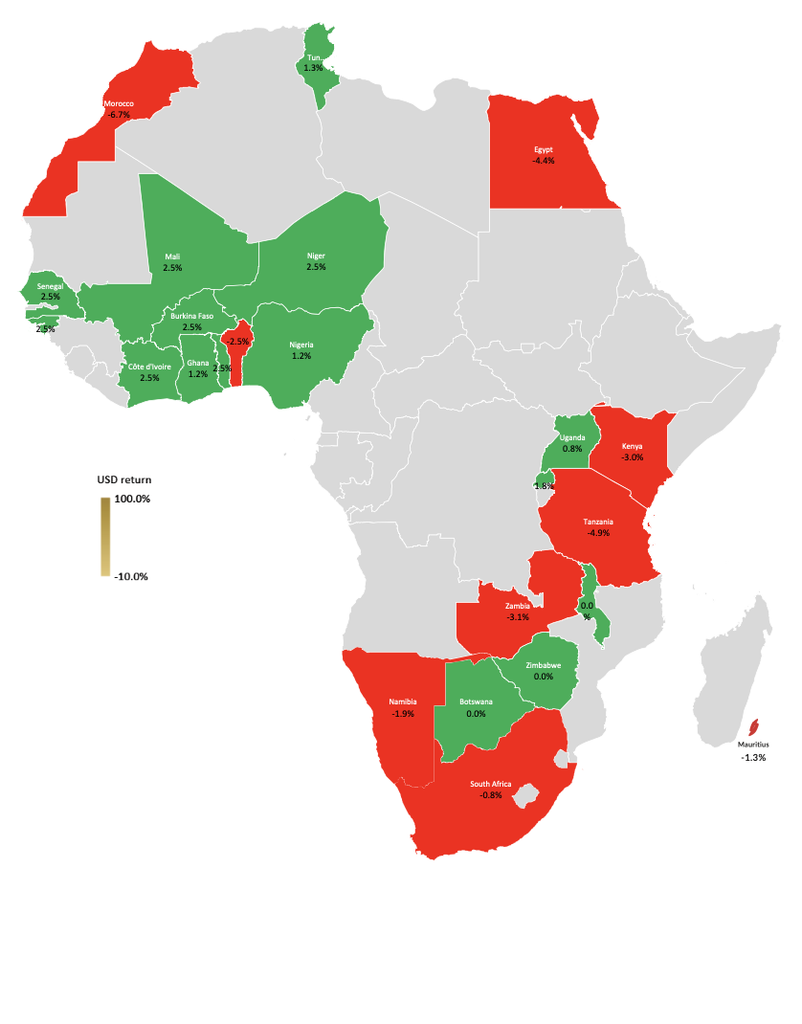
Select African countries’ benchmark index dollar returns